Intuit INTU is expanding its money ecosystem to drive growth beyond software subscriptions. Payments, Bill Pay, QuickBooks Capital and the Intuit Business Credit Card are helping the company monetize existing QuickBooks customers more deeply. The online money portfolio grew 31% in fiscal 2026, while total payment volume, including Bill Pay, surpassed $225 billion.
Payments remain a key growth driver. Payments revenues increased $257 million in fiscal 2026, supported by payments customer growth, increased transaction volume per customer and improved revenue yield. In fourth-quarter 2026, online payment volume, including Bill Pay, jumped 32%, while volume, excluding Bill Pay, increased 21%, highlighting growing adoption of the broader payments ecosystem.
Intuit also has room to boost monetization. QuickBooks Online Advanced customers have nine percentage points higher payments penetration than core QuickBooks Online users. Meanwhile, Online Ecosystem ARPC rose 15% in fiscal 2026 compared with only 3% growth in online paying customers, showing that deeper service adoption is becoming increasingly important.
Bill Pay, QuickBooks Free and the new Business Credit Card could strengthen this opportunity. However, slower customer growth remains a concern. QuickBooks Capital is also facing lower yields as more loans move to forward-flow partners, while scaling payments and lending is also adding to costs.
Payments appear capable of remaining a major growth engine for Intuit. Yet sustaining recent momentum will depend on broader adoption, rising transaction volumes and faster customer acquisition.
How Are Intuit’s Competitors Faring?
Block's XYZ Square competes in SMB payments, lending and banking. In the second quarter of 2026, Square GPV rose 13% year over year to $72.8 billion, while Square gross profit climbed 13% to $1.16 billion. Growth was driven mainly by stronger payments volume, increased software adoption and continued momentum in Square Loans.
Fiserv FISV competes with Intuit in SMB payments through Clover. In the second quarter of 2026, Clover’s annualized GPV reached $367 billion, while GPV rose 9% year over year. Clover revenues increased 13%, excluding certain impacts, and Fiserv’s Small Business adjusted revenues totaled $1.76 billion.
INTU’s Price Performance, Valuation and Estimates
Shares of Intuit have gained 14.1% over the past three months, underperforming the broader industry and outperforming the S&P 500 composite.
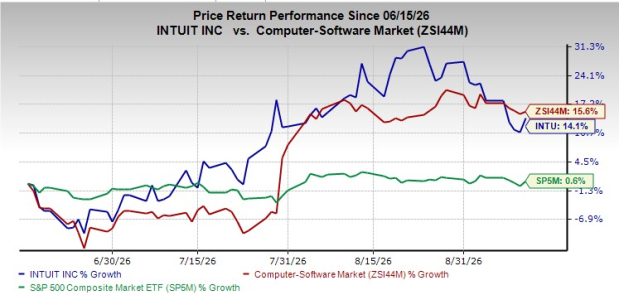
Image Source: Zacks Investment Research
In terms of forward 12-month Price/Sales (P/S), Intuit is currently trading at 3.63X, which is at a discount to the industry average of 6.12X.
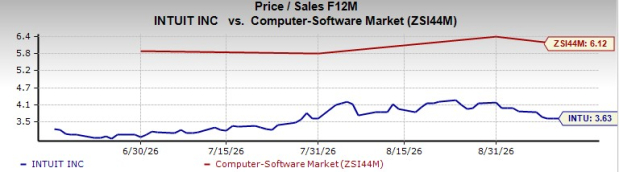
Image Source: Zacks Investment Research
Intuit’s estimate revisions reflect a negative trend. The Zacks Consensus Estimate for fiscal 2027 EPS has been revised downward 15.8% to $23.49 over the past month. The consensus estimate for 2026 calls for negative 3.2% growth year over year.
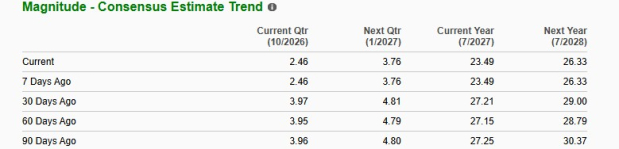
Image Source: Zacks Investment Research
Currently, Intuit carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Intuit Inc. (INTU): Free Stock Analysis Report
Fiserv, Inc. (FISV): Free Stock Analysis Report
Block, Inc. (XYZ): Free Stock Analysis ReportThis article originally published on Zacks Investment Research (zacks.com).
Zacks Investment Research