The Procter & Gamble Company’s PG Fabric & Home Care business is showing early signs of improvement, although performance remains uneven across categories and geographies. In the fourth quarter of fiscal 2026, Fabric Care delivered organic sales in line to up low single digits, while Home Care declined. For the full fiscal year, however, both categories were in line to up low single digits. Management also highlighted a meaningful inflection in U.S. Fabric Care and improving share trends in China. Nevertheless, competition has intensified in European Fabric Care, making the restoration of competitiveness in that market an important near-term priority.
A major catalyst for renewed momentum is P&G’s stepped-up innovation across its core laundry franchises. The company completed its biggest upgrade to original Tide liquid detergent in more than two decades, materially improving product performance without raising the price. Since the launch, Tide original liquid has moved from declining sales to high-single-digit growth, exceeding management’s expectations. Meanwhile, Tide evo, a proprietary unit-dose format backed by more than 50 granted patents, is progressing toward national expansion with full-scale launch support planned for fiscal 2027. Home Care is also benefiting from innovation, with Mr. Clean’s expanded Magic Eraser platform and Shower & Tub scrubber helping the brand capture 18 times its fair share of bath-cleaning category growth since launch.
Looking ahead, the segment appears well positioned to regain momentum if these innovations translate into broader user and market-share gains. Management sees substantial runway in Fabric Care, noting that the category has delivered growth of more than 5% over the past decade, supported by double-digit growth in adjacencies such as fabric enhancers. P&G is increasingly focused on strengthening established propositions while expanding into incremental consumption occasions, with Tide evo and fabric enhancers cited as innovations capable of lifting category growth. Still, competitive pressure in Europe and recent softness in Home Care remain key watchpoints. Overall, stronger core product performance, premium innovation and expanding adjacencies provide a credible path toward improving Fabric & Home Care growth over fiscal 2027.
CL & CHD Lean on Innovation to Sustain Household-Care Momentum
Both Church & Dwight CHD and Colgate-Palmolive CL are leveraging innovation, brand strength and household-care demand to support growth amid competitive pressures.
Church & Dwight is showing encouraging momentum across its household portfolio, supported by healthy demand, innovation and sustained brand investment. Growth in the Consumer Domestic business has been aided by strength in brands such as ARM & HAMMER and OXICLEAN, with volume gains indicating resilient consumer demand. The company continues to invest in product improvements, marketing and distribution to reinforce its competitive position across laundry, cleaning and other household categories. While performance can vary across brands, a strong portfolio of value-oriented and differentiated products, coupled with continued innovation, should help Church & Dwight maintain momentum in its household business.
Colgate, meanwhile, continues to strengthen its Home Care business through innovation, premiumization and focused brand support. Categories such as fabric softeners and surface cleaners have been important contributors, reflecting consumer demand for products that offer improved performance and convenience. Colgate’s strong brand equity and broad global distribution network also provide a solid platform for expanding household-care offerings across markets. Continued productivity initiatives and disciplined investment in advertising and innovation should support further progress. However, uneven consumer demand and competitive intensity remain watchpoints, making sustained product differentiation and effective execution important for maintaining Home Care momentum.
PG’s Price Performance, Valuation & Estimates
Procter & Gamble’s shares have lost around 4.5% in the past six months compared with the industry’s 4.8% decline.
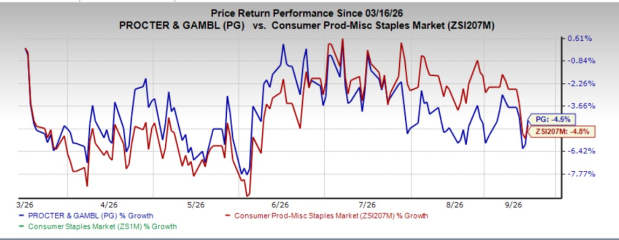
Image Source: Zacks Investment Research
From a valuation standpoint, PG trades at a forward price-to-earnings ratio of 20.5X compared with the industry’s average of 18.2X.
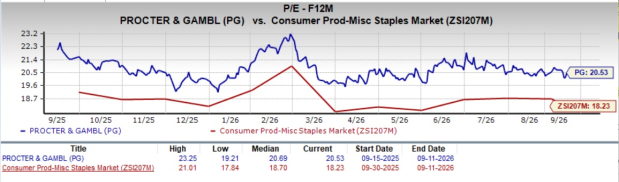
Image Source: Zacks Investment Research
The Zacks Consensus Estimate for PG’s fiscal 2026 and 2027 EPS indicates year-over-year growth of 1.5% and 6.2%, respectively. The company’s EPS estimates for fiscal 2026 and 2027 have remained stable in the past seven days.
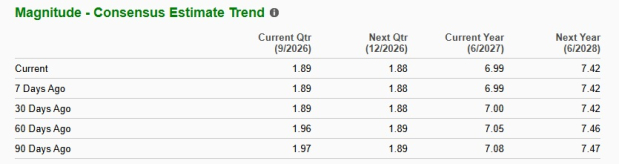
Image Source: Zacks Investment Research
Procter & Gamble currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Procter & Gamble Company (The) (PG): Free Stock Analysis Report
Colgate-Palmolive Company (CL): Free Stock Analysis Report
Church & Dwight Co., Inc. (CHD): Free Stock Analysis ReportThis article originally published on Zacks Investment Research (zacks.com).
Zacks Investment Research