Macy's, Inc. M looks inexpensive on a relative basis after shares fell 8.5% in the past three months. At $22.08 on Sept. 11, the stock traded at a forward 12-month price-to-earnings ratio of 9.39, below 13.33 for the Zacks sub-industry, 21.60 for the Zacks sector and 19.84 for the S&P 500.
That discount is backed by better second-quarter execution and raised fiscal 2026 guidance. The caution is the second half, where third-quarter comparable sales are expected to range from a 0.5% decline to a 0.5% increase and adjusted earnings are projected to be negative.
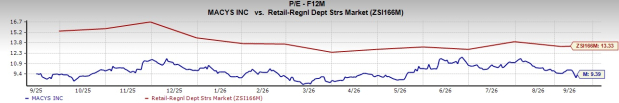
Image Source: Zacks Investment Research
Macy's Valuation is Cheap, But Not Versus Its Own History
The relative valuation discount is clear. Macy's forward 12-month price-to-earnings ratio sits well below its sub-industry and broad-market benchmarks, giving value-oriented investors a reason to keep the stock on the radar.
Its own history is less compelling. Over the past five years, the ratio has ranged from 3.56 to 11.76, with a median of 6.19. The current valuation is above the five-year median, while the shares have already gained 30.3% in the past year.
Q2 Momentum Gives the Discount Support
Second-quarter net sales increased 1.1% to $4.866 billion and comparable sales rose 2.7%. Excluding the 23-cent net tariff refund benefit, adjusted earnings were 40 cents per share compared with 35 cents a year earlier. Underlying gross margin improved about 10 basis points after excluding tariff refund and tariff-and-fuel effects.
Growth also broadened across the portfolio. Bloomingdale's comparable sales rose 11.3%, Bluemercury increased 6.2% and Reimagine 200 locations gained 1.9%. Macy's ended the quarter with $1.29 billion in cash, while first-half operating cash flow increased to $586 million from $255 million.
Second-Half Growth is the Main Constraint
Third-quarter net sales are projected at $4.65-$4.70 billion, with adjusted earnings expected at a loss of 19-23 cents per share. Macy's raised full-year comparable-sales guidance to growth of 1-1.5% and adjusted earnings guidance to $2.15-$2.35 per share, but management kept its underlying second-half sales assumptions unchanged.
Investment spending also limits near-term operating leverage. Macy's expects selling, general and administrative expenses to rise 1.5-2.25% for fiscal 2026 and plans to reinvest $96 million of tariff refunds in brand building, value initiatives and Reimagine pilots. Fiscal 2025 store closures also create about a $145 million annual sales comparison headwind.
Retail Competition Keeps Execution Risk Elevated
Kohl's Corporation KSS reported a 0.9% second-quarter comparable-sales decline while raising its fiscal 2026 outlook, highlighting the mixed demand backdrop in department-store retail.
Target Corporation TGT reported 3.8% comparable-sales growth and an 8.7% increase in digital comparable sales in its second quarter. That performance raises the bar for retailers competing on assortment, value and convenience as Macy's works to sustain traffic through fall and holiday.
What Should Investors Do With Macy's Stock?
Macy's looks inexpensive relative to its industry and the broader market, but the stock is not unusually cheap compared with its own five-year history. Better execution, luxury-banner momentum and liquidity support the case, while soft third-quarter guidance and a heavy investment agenda argue against treating valuation alone as a buy signal.
The stock currently carries a Zacks Rank #3 (Hold), with a VGM Score of A, Value Score of A, Growth Score of B and Momentum Score of A. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
The favorable Style Scores support the value and momentum profile, but they are designed to complement the Zacks Rank. For now, the #3 Rank supports a measured stance until second-half growth and operating leverage become more consistent.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Macy's, Inc. (M): Free Stock Analysis Report
Target Corporation (TGT): Free Stock Analysis Report
Kohl's Corporation (KSS): Free Stock Analysis ReportThis article originally published on Zacks Investment Research (zacks.com).
Zacks Investment Research