TTM Technologies TTMI stock is trading at a low Price/Sales (P/S) multiple, below the Zacks Electronics - Miscellaneous Components industry and broader tech sector averages. TTMI’s 2.59X forward 12-month P/S multiple compares favorably with the 3.74X industry average and 6.05X Computer and Technology sector average.
TTMI also trades at a cheaper valuation compared with several industry peers, including nVent Electric NVT, Ouster OUST and Vicor VICR. nVent Electric carries a forward P/S multiple of 4.28X, while Ouster and Vicor trade at significantly higher multiples of 9.17X and 10.39X, respectively.
Price/Sales Ratio (F12M)

Image Source: Zacks Investment Research
The valuation discount appears particularly attractive, given TTM Technologies’ exposure to the expansion of AI-driven data centers, strong demand in the defense sector and improving margins. The company is also converting its capacity-related investments into higher earnings, strengthening the case for further growth. Importantly, management targets 15–20% annual revenue growth and aims to double its earnings between 2025 and 2027.
While a low P/S ratio often means a stock is a good value, it can also be a warning sign. Therefore, investors need to examine whether TTM Technologies’ valuation discount is justified by its business risks or whether the market is underappreciating its growth and earnings potential. Let’s analyze.
AI Data-Center Demand Positions TTMI for Long-Term Growth
TTM Technologies has built a strong long-term growth position in the AI data-center market, supported by rapidly rising demand and increasing adoption of its advanced interconnect technologies. Data Center and Networking accounted for 40% of second-quarter 2026 sales, while revenues from the end market surged 91% year over year, reflecting strong demand from customers building out AI data centers. TTMI expects this market to represent 49% of third-quarter sales, with the early stages of the N+M production ramp contributing to growth. For full-year 2026, the company expects Data Center and Networking sales to more than double year over year.
The N+M asymmetrical interconnect PCB ramp provides an additional long-term opportunity. TTM Technologies completed Phase 1 factory expansions to support key customer NPI programs and the third-quarter mass-production ramp. The company had already delivered tens of millions of dollars of N+M products, with approximately $600 million of additional N+M business expected in the second half of 2026. Improving yields during the production ramp are also expected to support margins.
Notably, management remains confident in achieving 15%-20% organic revenue growth in 2027 and 2028, supported by continued AI and defense demand.
TTMI’s Defense Backlog Provides Growth Visibility
TTM Technologies' aerospace and defense business provides substantial long-term revenue visibility through a combination of strong current demand, a growing program backlog and a sizable qualified opportunity pipeline. A&D represented 37% of second quarter 2026 sales, with revenues increasing 14% year over year, supported by favorable defense-budget trends, strategic program alignment and bookings for new and ongoing programs.
The most important indicator of future opportunity is the 1.3 A&D book-to-bill ratio, which helped increase TTM Technologies' total program backlog to $1.7 billion, up from $1.5 billion a year earlier. Beyond existing backlog, the company has more than $7 billion of potential business qualified in its strategic pipeline, representing a substantial pool of opportunities as the programs reach the contract execution stage. Recent bookings include the APS-153 multi-mode maritime surveillance radar, ATP Sensor System, Golden Dome and priority restricted programs.
TTM Technologies is also expanding beyond traditional PCB manufacturing into integrated electronics, RF modules, subsystems and complete radar systems, potentially allowing it to capture greater value from increasingly complex defense programs. Its new Syracuse facility is beginning the Ultra-HDI ramp, with full-capacity run rate expected in 2028, adding another potential source of long-term A&D growth.
TTMI Stock Outperforms Industry, Sector & S&P 500
TTM Technologies shares have surged 83.2% in the year-to-date period, significantly outperforming the industry’s decline of 16.2%, the broader technology sector and the Zacks S&P 500 Index’s growth of 18.5% and 11.4%, respectively.
The stock has also outpaced key peers, including nVent Electric, Ouster and Vicor, whose shares soared 59.2%, 63.2% and 80.5%, respectively. TTMI’s strong performance is supported by favorable AI infrastructure and data-center trends; meanwhile, the company's planned acquisitions could further bolster its long-term growth by expanding its technology, customer base and geographic reach.
TTMI’s YTD Price Performance
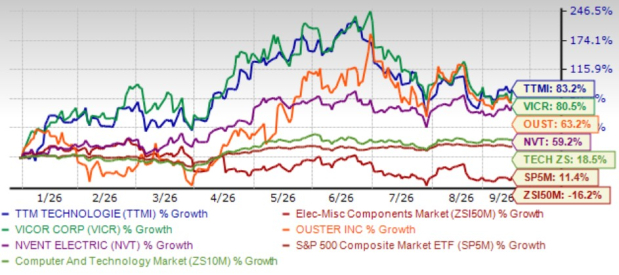
Image Source: Zacks Investment Research
Positive Analyst Sentiment for TTMI
The Zacks Consensus Estimate for TTMI’s third-quarter 2026 earnings is pegged at $1.25 per share, reflecting an 11.6% upward revision over the past 60 days and projecting a solid 86.6% increase from the year-ago period.
The consensus mark for 2026 earnings is pegged at $4.82 per share, up 17.9% over the past 60 days, indicating strong confidence in TTM Technologies' growth outlook and robust 95.9% year-over-year earnings growth.
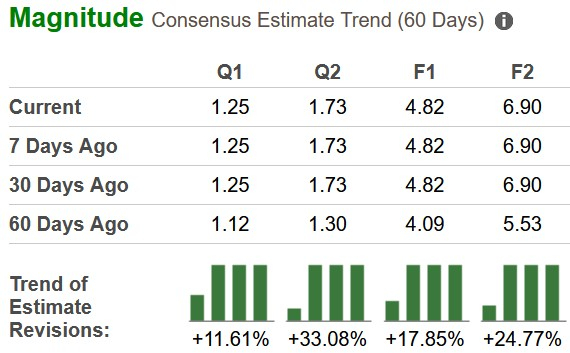
Image Source: Zacks Investment Research
Conclusion: A Chance to Buy TTMI Stock
TTM Technologies’ growth prospects remain encouraging, supported by accelerating AI data-center demand, strong defense bookings and the N+M technology ramp. Its valuation also remains reasonable relative to peers despite the stock’s significant gains. Rising earnings estimates further strengthen the outlook. Given these growth drivers and valuation support, TTMI stock appears to present an attractive buying opportunity for investors seeking long-term upside.
TTM Technologies currently sports a Zacks Rank #1 (Strong Buy). You can see the complete list of today’s Zacks #1 Rank stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
TTM Technologies, Inc. (TTMI): Free Stock Analysis Report
Vicor Corporation (VICR): Free Stock Analysis Report
nVent Electric PLC (NVT): Free Stock Analysis Report
Ouster, Inc. (OUST): Free Stock Analysis ReportThis article originally published on Zacks Investment Research (zacks.com).
Zacks Investment Research