Shares of W.R. Berkley Corporation WRB are trading at a premium compared with the industry. Its trailing 12-month price-to-book value of 2.64X is higher than the industry average of 1.44X, but lower than the Finance sector’s 4.39X and the Zacks S&P 500 composite’s 8.16X. However, the insurer has a Value Score of B.
W. R. Berkley’s premium growth, international expansion, technology investments and strong capital position support diversified operations and growth. Earnings delivered a compound annual growth rate (CAGR) of 22.5% over the past five years, while WRB beat earnings estimates in three of the trailing four quarters, with an average of 8.4%.
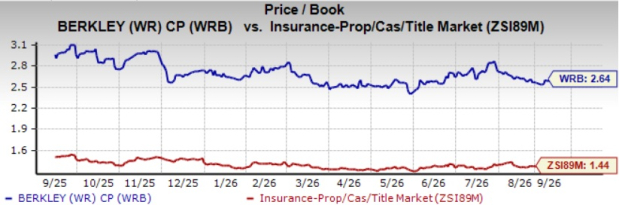
Image Source: Zacks Investment Research
Shares of other P&C insurers, such as The Allstate Corporation ALL, RLI Corp. RLI, and The Progressive Corporation PGR, are also trading at multiples above the industry average.
WRB’s Price Performance
WRB shares have declined 4% against the industry’s growth of 4.4% in a year.
Shares of other insurers like ALL have gained 31%, while RLI and PGR have lost 8.3% and 11.4%, respectively, in a year.
1-Year Price Performance: WRB, RLI, ALL, PGR & Industry
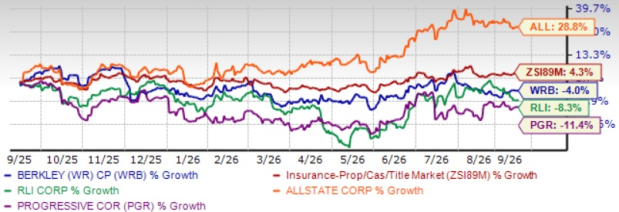
Image Source: Zacks Investment Research
WRB’s Encouraging Growth Projection
The Zacks Consensus Estimate for W.R. Berkley’s 2026 earnings per share (EPS) indicates a year-over-year increase of 12.5%. The consensus estimate for revenues is pegged at $15.1 billion, implying a year-over-year improvement of 3.3%.
The consensus estimate for 2027 EPS indicates a decrease of 0.5%, while revenues suggest an improvement of 3.1% from the corresponding 2026 estimates.
The expected long-term earnings growth is pegged at 8.3%.
Optimistic Analyst Sentiment on WRB
The Zacks Consensus Estimate for 2026 and 2027 has moved 0.8% and 0.4% north, respectively, in the last 30 days.
Efficient Use of Shareholder Capital
Return on equity for the trailing 12 months was 19.4%, which compared favorably with the industry’s 7.5%. This reflects its efficiency in utilizing shareholders’ funds.
Factors Acting in Favor of WRB Stock
W. R. Berkley continues to benefit from disciplined underwriting and prudent risk selection. Pretax underwriting income reached $318 million in the second quarter, while the current accident-year combined ratio, excluding catastrophes, was 88.1%, reflecting healthy margins despite moderating pricing. Strong cost discipline, reflected in the second-quarter expense ratio of 28.5%, which was better than management’s expectation, should support margins and overall underwriting profitability.
Record net investment income is providing an additional earnings tailwind. In the second quarter of 2026, pre-tax net investment income reached a record $419 million, while the core portfolio income increased 13% year over year to $371 million. Record net invested assets and higher new money rates on a growing fixed maturity portfolio, along with strong operating cash flows, are driving net investment income.
W. R. Berkley continues to benefit from its diversified specialty insurance platform. Its broad portfolio spans liability, commercial, auto, professional liability and workers’ compensation, while its reinsurance business provides additional diversification. International expansion across Asia-Pacific, South America and Mexico has further strengthened its geographic reach. This strategy has supported an 8.8% CAGR in insurance premiums written from 2018 to 2025, with gross and net premiums reaching record levels in 2025.
WRB continues to see favorable growth opportunities across casualty, accident and health (A&H) and private-client personal lines. Management remains confident in its ability to deploy capital toward areas offering attractive risk-adjusted returns, while the broader casualty market continues to provide opportunities for profitable growth.
The insurer is leveraging AI across underwriting, claims, risk assessment, customer service, fraud detection and marketing. Early implementations have improved underwriting efficiency by more than 20%, supporting operating leverage. Management expects further productivity gains as AI adoption expands.
W.R. Berkley maintains a solid balance sheet with sufficient liquidity and strong cash flows. As of June 30, 2026, the company had cash and cash equivalents of nearly $2.4 billion. The company returned $334 million through dividends and share repurchases in the second quarter of 2026, while capital returned over the preceding 12 months exceeded $1.3 billion.
Risks for WRB
WRB’s expanding international operations expose it to increased political, legal, regulatory and economic risks, including foreign currency and credit risk, which could have an adverse effect on its results of operations and financial condition.
Intense competition across the insurance and reinsurance markets remains a key headwind. It can affect the profitability of existing and new businesses.
Conclusion
W. R. Berkley’s underwriting discipline, premium growth, international expansion, higher investment income, technology investments and consistent cash flow support diversified operations and long-term growth. Solid capital returns, higher ROE and optimistic analyst sentiment are other positives.
However, premium valuation, stiff competition and exposure to foreign currency and credit risk are the risks. We prefer to stay cautious on this Zacks Rank #3 (Hold) stock. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
W.R. Berkley Corporation (WRB): Free Stock Analysis Report
RLI Corp. (RLI): Free Stock Analysis Report
The Allstate Corporation (ALL): Free Stock Analysis Report
The Progressive Corporation (PGR): Free Stock Analysis ReportThis article originally published on Zacks Investment Research (zacks.com).
Zacks Investment Research