DexCom, Inc. DXCM is well positioned for growth in the coming quarters, supported by the significant potential of the continuous glucose monitoring (CGM) market. A strong first-quarter 2026 performance and a robust international foothold are expected to contribute further. Risks related to stiff competition persist.
This Zacks Rank #3 (Hold) company’s shares have gained 26.9% so far this year against the industry’s 10.8% decline. The S&P 500 Index has gained 11.4% in the same time frame.
DXCM, a renowned medical device company and provider of CGM systems, has a market capitalization of $31.33 billion. It projects a 22.6% growth rate over the next five years and anticipates maintaining a strong performance going forward.
DexCom’s earnings surpassed the Zacks Consensus Estimate in each of the trailing four quarters, the average surprise being 11.39%.
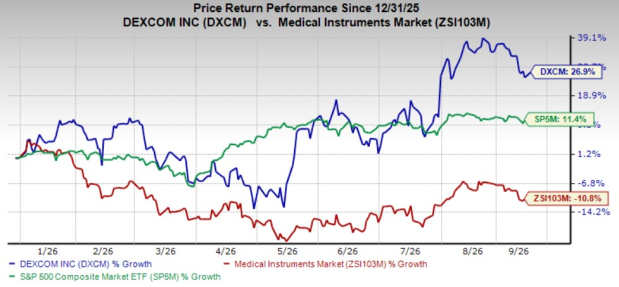
Image Source: Zacks Investment Research
Let’s delve deeper.
Positive Drivers
Strong Global Demand and Share Gains Support Durable Growth: Dexcom delivered a strong second quarter, with worldwide revenues rising 13% year over year to $1.31 billion and organic growth reaching 12%. U.S. revenues increased 11% to $933 million, supported by strong new-patient additions and share gains, while international revenues climbed 19% to $375 million, with organic growth of 16%.
Global new customer additions remained near the record level achieved in the first quarter, while new customers in the United States increased sequentially. Growth across Type 1, Type 2 intensive, basal and non-insulin populations suggests that momentum is not dependent on a single patient category, enhancing the durability of Dexcom’s near-term growth trajectory.
CONNECT Could Unlock a Substantially Larger Non-Insulin Type 2 Market: The CONNECT trial materially strengthens Dexcom's case for expanding CGM reimbursement among non-insulin Type 2 diabetes patients. The nearly 300-patient randomized study showed a 1.6% A1c improvement in the Dexcom group and a 0.9% advantage versus control, alongside more than five additional hours per day in normal glucose range and 97% median CGM utilization.
Commercial coverage already spans the four largest PBMs, representing more than 7 million non-insulin Type 2 patients. Dexcom has submitted the evidence to CMS and expects a coverage decision by year-end, with implementation targeted for mid-2027. Successful Medicare expansion could substantially enlarge the company's addressable market.
G7 15 Day Adoption Should Strengthen Product Differentiation and Margins: The G7 15 Day system is emerging as an important product-cycle catalyst, combining longer wear time, algorithm improvements and better customer experience. Dexcom said Net Promoter Scores have increased for three consecutive quarters, while integration with Tandem and Mobi now makes the system available to all adult G7 customers in the United States.
Management remains on track to convert nearly 50% of its U.S. customer base by year-end, with adoption expected to contribute increasingly in the second half and become more meaningful in 2027. The product transition is also improving the margins. The second-quarter gross margin expanded 400 basis points to 64.1%, aided by manufacturing efficiencies and the initial G7 15 Day mix shift.
Risks
CMS Reimbursement Remains a Critical Execution and Timing Risk: A major portion of DexCom's longer-term growth thesis depends on expanding CGM coverage to the large non-insulin Type 2 population, but the business remains contingent on regulatory and reimbursement decisions. Management expects to hear from CMS on the coverage decision before year-end, while planning for implementation only around mid-2027. This creates a potentially lengthy period between evidence submission and revenue realization.
Moreover, commercial physician awareness still requires significant education because hundreds of thousands of prescribers must understand where reimbursement exists. Any restrictive CMS coverage criteria, implementation delays or slower physician adoption could postpone the expected acceleration in patient additions, leaving the company’s near-term growth more dependent on already-covered populations.
International Growth Faces Tougher Comparisons: International operations remain a major growth engine, but the second half carries greater execution risk. Second-quarter international organic revenue growth was an impressive 16%, supported by reimbursement gains in markets such as France and Canada. However, management acknowledged that year-over-year comparisons in the third and fourth quarters will become tougher because of significant access gains achieved during the second half of 2025.
Management cited the euro exchange rate as an important modeling factor and expects currency movements to negatively impact international revenues compared with previous guidance. Although the underlying market opportunity exceeds 60 million potential lives across key international markets, tender timing, reimbursement expansion and foreign-exchange volatility could make reported growth less consistent through the remainder of 2026.
Stelo and Nutrisense Have Limited Near-Term Revenue Impact: Dexcom's expansion into consumer metabolic health is strategically promising, but investors should distinguish platform development from immediate financial contribution. Management acknowledged that the incremental non-CGM revenue from Nutrisense is only in the low millions, with most existing revenue essentially representing Stelo CGM pass-through sales.
Therefore, the acquisition's primary rationale is technology, engagement and personalized nutrition insights rather than near-term revenue acceleration. Similarly, the redesigned Stelo app is intended to improve engagement and create a broader platform for future G-series functionality, but its commercial impact remains unproven. This means Dexcom must continue funding innovation while relying primarily on its core CGM business for growth until these newer initiatives achieve meaningful monetization.
Estimate Trend
DexCom has witnessed a positive estimate revision trend for 2026. In the past 60 days, the Zacks Consensus Estimate for 2026 earnings per share has moved north 7 cents to $2.64.
The consensus mark for the company’s third-quarter revenues is pegged at $1.32 billion, indicating an 9.4% improvement from the year-ago quarter’s reported number. The consensus estimate for third-quarter earnings is pinned at 66 cents per share, implying an improvement of 8.2% year over year.
Stocks to Consider
Some better-ranked stocks from the broader medical space are Veracyte VCYT, Globus Medical GMED and West Pharmaceutical WST.
Veracyte, currently sporting a Zacks Rank #1 (Strong Buy), reported second-quarter 2026 adjusted earnings per share (EPS) of 54 cents, which surpassed the Zacks Consensus Estimate by 25.6%. Revenues of $150.3 million beat the Zacks Consensus Estimate by 4.1%. You can see the complete list of today’s Zacks #1 Rank stocks here.
VCYT has an estimated earnings growth rate of 8.4% for 2026. The company’s earnings beat estimates in each of the trailing four quarters, the average surprise being 41.8%.
Globus Medical, currently sporting a Zacks Rank #1, reported second-quarter 2026 adjusted EPS of $1.34, which surpassed the Zacks Consensus Estimate by 19.6%. Revenues of $789.6 million beat the Zacks Consensus Estimate by 0.4%.
GMED has an estimated long-term earnings growth rate of 12.4%. The company’s earnings beat estimates in each of the trailing four quarters, the average surprise being 27.9%.
West Pharmaceutical, carrying a Zacks Rank #2 (Buy) at present, reported second-quarter 2026 adjusted EPS of $2.37, which beat the Zacks Consensus Estimate by 13.9%. Revenues of $872.3 million surpassed the Zacks Consensus Estimate by 4.2%.
WST has an estimated long-term earnings growth rate of 16%. WST’s earnings surpassed estimates in each of the trailing four quarters, the average surprise being 17.4%.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
DexCom, Inc. (DXCM): Free Stock Analysis Report
West Pharmaceutical Services, Inc. (WST): Free Stock Analysis Report
Globus Medical, Inc. (GMED): Free Stock Analysis Report
Veracyte, Inc. (VCYT): Free Stock Analysis ReportThis article originally published on Zacks Investment Research (zacks.com).
Zacks Investment Research