Over the past year, Blue Dolphin Energy Co. BDCO has skyrocketed 629.4%, significantly outperforming peers Marathon Petroleum Corporation MPC and PBF Energy PBF, which have surged 73.2% and 61.6%, respectively. The BDCO stock has also comfortably outpaced the sub-industry’s 5.7% return and the S&P 500’s 13.9% advance during the same period.
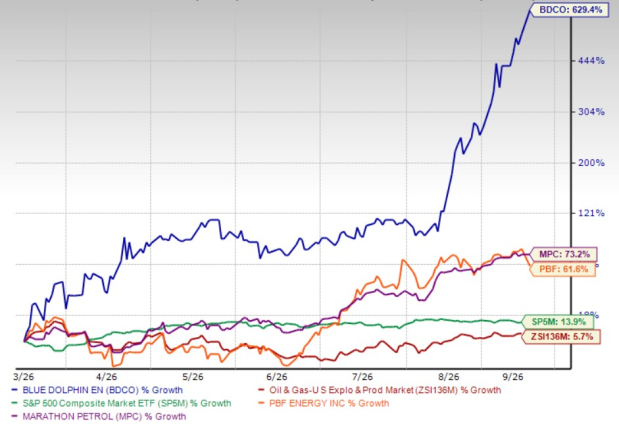
Image Source: Zacks Investment Research
The price chart reflects investors' strong preference for the BDCO stock. However, before making investment decisions, one should consider the company's overall business environment and fundamentals.
Operational Improvements & Stronger Margins Aid BDCO
Blue Dolphin's operating performance improved substantially in the second quarter of 2026. Refinery revenues surged to $143.5 million from $55.8 million a year earlier, reflecting higher sales volumes and more favorable market pricing. Sales volumes increased 56.3%, while refining EBITDA improved to $23.8 million from a loss of $0.9 million. Refinery downtime also dropped to just one day from 14 days in the year-ago quarter.
The company has also been working to improve the efficiency and reliability of its Nixon refinery. In the first half of 2026, Blue Dolphin refurbished or replaced components, including the naphtha stabilizer heater, boiler deaerator, crude oil desalter and crude oil charge pump. Management expects these upgrades to improve product yields, while reducing energy costs and refinery downtime, which should support operational efficiency.
Liquidity has strengthened considerably as well. Cash and cash equivalents increased to $30.7 million as of June 30, 2026, from roughly $1 million at 2025-end. BDCO generated $39 million in operating cash flow during the first half of 2026 and made $9.2 million of third-party and related-party debt-principal payments. The stronger cash position provides greater flexibility to meet working-capital requirements, fund refinery operations and service debt.
EIA Outlook Signals Near-Term Margin Support for BDCO
The U.S. Energy Information Administration (EIA) expects a supportive near-term backdrop for distillate margins. The agency lifted its 2026 U.S. distillate crack-spread forecast to $1.57 per gallon from $1.30 and raised its 2027 projection to $1.25 from 97 cents, suggesting increases of 20.8% and 28.5%, respectively.
The agency also expects U.S. distillate inventories to fall below 100 million barrels in September and remain below the five-year low through the end of 2026 and much of 2027. Moreover, average U.S. diesel crack spreads are projected to exceed $2 per gallon from August through November before declining steadily through mid-2027.
This environment could support BDCO because the Nixon refinery produces jet fuel, as well as intermediate products such as naphtha, heavy oil-based mud blendstock and atmospheric gas oil. Stronger distillate markets could therefore support realized product pricing and refining margins.
Per EIA, Brent crude is expected to average $90 per barrel in the second half of 2026, which could keep BDCO's feedstock costs elevated. The agency also expects oil prices and diesel crack spreads to ease as Middle East supply flows gradually recover and global inventories rebuild. Thus, the outlook suggests strong near-term margin support but also points to the possibility of margin normalization in 2027.
Debt Defaults & Commodity Volatility Remain Key Risks
Despite the improved operating picture, BDCO continues to face significant financial risks. As of June 30, 2026, $30.5 million of the current portion of long-term debt was classified as in default. Blue Dolphin's LE and LRM subsidiaries were in default on financial covenants under their Huntington loans, while NPS was in default on non-financial covenants under its GNCU loan. These defaults could permit lenders to accelerate repayment, exercise rights over collateral or pursue other remedies, which could materially pressure BDCO's cash position.
Blue Dolphin continues to engage potential lenders to obtain additional financing and refinance or restructure its debt. However, management cautioned that there is no assurance that it will be able to raise additional capital on acceptable terms or successfully refinance existing obligations.
Commodity-price volatility poses another key risk. Management noted that Blue Dolphin's operating results and liquidity are highly dependent on the margin between crude oil and condensate input costs and refined-product selling prices. These spreads have historically fluctuated widely, and any narrowing could affect the company's earnings, cash flow and liquidity.
BDCO Trades at a Discount
Blue Dolphin appears attractively valued relative to the broader industry. The stock currently trades at a trailing 12-month enterprise value-to-EBITDA, or EV/EBITDA, multiple of 5.12, well below the industry average of 11.3.
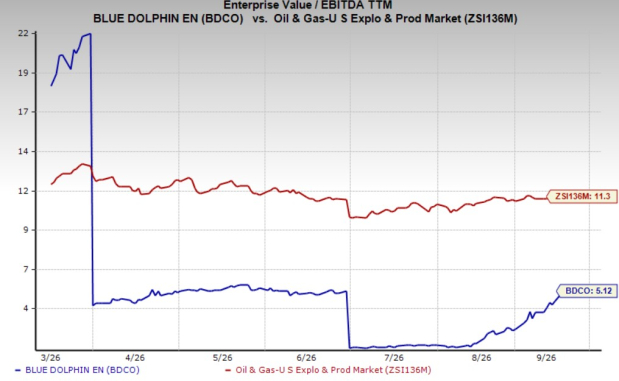
Image Source: Zacks Investment Research
The valuation discount could make the stock appear appealing, particularly given the sharp improvement in operating performance and liquidity. However, investors should weigh this discount against BDCO's debt defaults, commodity-price exposure and the possibility that today's unusually favorable refining environment may not persist.
Should You Bet on BDCO Stock?
Blue Dolphin's fundamentals have improved meaningfully. Higher sales volumes, stronger refining margins, sharply reduced downtime and a much healthier cash position provide support to the company's operating outlook. The near-term distillate market is also favorable, with low inventories and elevated crack spreads potentially benefiting BDCO's refined-product pricing.
However, the stock's massive rally has already priced in considerable optimism. More importantly, the company's debt situation remains a major concern, with more than $30 million in current long-term debt classified as in default. BDCO's earnings are also highly sensitive to the spread between crude input costs and refined-product prices, while the EIA expects crack spreads to moderate as supply conditions normalize.
Therefore, despite BDCO's strong operating momentum and relatively inexpensive valuation, investors may want to refrain from chasing the stock after its steep rally. Greater clarity on debt refinancing and the sustainability of refining margins would make the risk-reward profile more compelling. For now, staying on the sidelines appears to be the more prudent approach.
7 Best Stocks for the Next 30 Days
Just released: Experts distill 7 elite stocks from the current list of 220 Zacks Rank #1 Strong Buys. They deem these tickers "Most Likely for Early Price Pops."
Since 1988, the full list has beaten the market more than 2X over with an average gain of +23.9% per year. So be sure to give these hand picked 7 your immediate attention.
See them now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Blue Dolphin Energy Co. (BDCO): Free Stock Analysis Report
Marathon Petroleum Corporation (MPC): Free Stock Analysis Report
PBF Energy Inc. (PBF): Free Stock Analysis ReportThis article originally published on Zacks Investment Research (zacks.com).
Zacks Investment Research