The microcomputer space is being driven by AI-enabled PCs, enterprise device refresh cycles, and the growing adoption of hybrid work. Rising demand for high-performance computing, cloud-connected workflows and enhanced cybersecurity is accelerating hardware upgrades. Advancements in processors, on-device AI capabilities and energy-efficient architectures are supporting premiumization, while the approaching end of support for older operating systems is expected to further stimulate commercial PC replacement demand.
Against this backdrop, let’s assess which company offers stronger long-term growth prospects — Lenovo Group LNVGY or HP Inc. HPQ.
Lenovo Group is a global technology leader with a diversified presence across PCs, enterprise infrastructure and intelligent solutions. HP is a global provider of personal computing and other access devices, imaging and printing products, and related technologies, solutions and services.
The Case for LNVGY
Lenovo remains one of the largest PC makers globally, but it's steadily transforming into a broader technology company, which should support stronger long-term growth. By pushing into higher-margin segments—AI infrastructure, hybrid cloud, enterprise services, and AI-enabled devices—Lenovo is lowering its dependence on the cyclical PC business and building new revenue streams.
The Intelligent Devices Group continues to generate strong cash flow, driven by commercial PC upgrade cycles, premium-product demand and rising AI PC adoption. At the same time, the Infrastructure Solutions Group is emerging as a key growth engine, benefiting from surging demand for AI servers, data-center hardware and high-performance computing. An AI server order backlog topping $21 billion gives solid forward revenue visibility.
Lenovo is also scaling its enterprise AI offerings. Its NVIDIA-developed Hybrid AI Advantage platform enables scalable, real-time AI inference across cloud and on-premise deployments, while the Infinidat acquisition deepens its foothold in high-end enterprise storage and opens further paths to revenue and margin gains.
Geographic diversification across Asia, Europe, and the Americas reduces reliance on any one region, and Lenovo's long-standing ties with enterprises, governments, and channel partners reinforce its market position. Continued investment in both Personal AI and Enterprise AI reflects its ambition to become a full-stack AI player, backed by disciplined cost control, solid cash generation, a conservative balance sheet and steady dividends.
Risks remain. Global PC shipments fell 2% last quarter (though Lenovo held a 25.6% share). Rising memory costs tied to AI-driven demand could squeeze margins. U.S.-China trade tensions pose ongoing cost and market-access risks.
The Case for HPQ
HP's growing AI PC mix, gains in premium computing and broader reach into workstations, workforce solutions, and industrial printing are helping shift its revenue and profit mix in a favorable direction.
Personal Systems has become HP's key growth engine. The fiscal third quarter marked the tenth consecutive quarter of revenue growth, driven by solid performance across both commercial and consumer segments. Demand should stay firm on the back of enterprise device replacement cycles, the ongoing Windows 11 transition, and rising adoption of AI-capable PCs.
Management estimates AI PC portfolio shipment to be 50% of total shipment mix by the end of this fiscal year. These AI PCs tend to lift product mix, since buyers are often willing to pay a premium for local AI processing, stronger security, and better power efficiency. HP is also pushing beyond pure hardware into software, device management, and its Workforce Experience Platform—moves that could strengthen customer relationships and build more recurring revenues.
Printing continues to drive HP's earnings. Supplies, managed print services, and contract-based offerings deliver steady recurring income that cushions the cyclicality of hardware. Still, the ongoing shift to digital workflows, softer home-printing demand, and third-party supplies competition create structural headwinds. Growth in industrial graphics, packaging, and subscription printing will need to offset declines in legacy categories.
Overall, HP's strengths—solid positioning in PCs and printing, reliable cash generation, expanding AI-device exposure, and steady capital returns—rest on a durable base of a large commercial customer base, global distribution reach, and a profitable print franchise. Its raised fiscal full-year 2026 outlook (free cash flow of $3.0–$3.2 billion, non-GAAP EPS of $3.19–$3.29) supports continued dividends, buybacks and reinvestment.
Successful AI PC uptake, commercial refresh demand, services growth, and cost discipline could drive EPS gains even in mature markets.
Estimates for LNVGY and HPQ
The Zacks Consensus Estimate for LNVGY’s fiscal 2027 and 2028 revenues implies a 32% and 20% year-over-year increase, respectively. EPS estimates for fiscal 2027 and 2028 imply a 66% and 58.4% year-over-year increase, respectively. EPS estimates for 2026 and 2027 have moved up 26.3% and 55.6%, respectively, in the past 30 days.
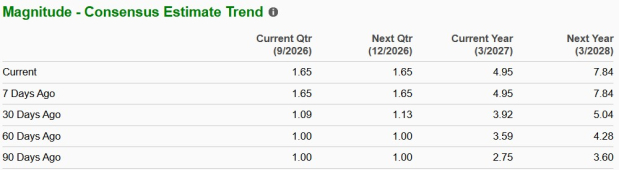
Image Source: Zacks Investment Research
The Zacks Consensus Estimate for HPQ’s fiscal 2026 and 2027 revenues implies an 8.5% and a 0.7% year-over-year increase, respectively. EPS estimates for fiscal 2026 and 2027 indicate a 3.5% increase and a 5% year-over-year decrease, respectively. EPS estimates for 2026 and 2027 have moved up 8.4% and 4.8%, respectively, in the past 30 days.
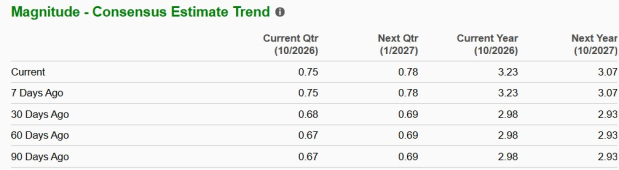
Image Source: Zacks Investment Research
Price Performance of LNVGY and HPQ
LNVGY shares have gained 26% in the past three months, while HPQ shares have gained 40% in the same time.
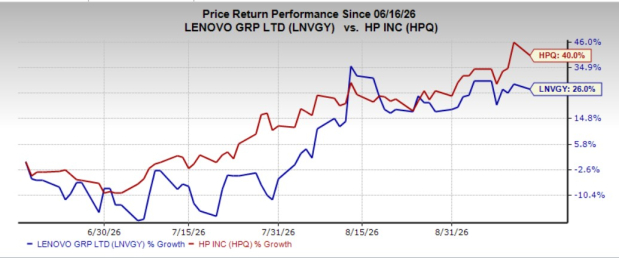
Image Source: Zacks Investment Research
Are LNVGY and HPQ Shares Expensive?
LNVGY is trading at a forward 12-month price-to-sales multiple of 0.43, higher than its median of 0.23 over the past three years. HPQ’s forward 12-month price-to-earnings multiple sits at 0.51, slightly higher than its median of 0.48 over the past three years.
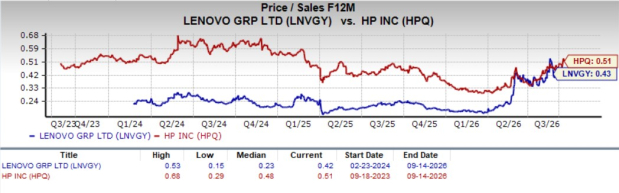
Image Source: Zacks Investment Research
Conclusion
Lenovo Group presents an attractive investment opportunity, supported by its leading position in the global PC market, growing AI-related demand and improving profitability. Management targets $100 billion in revenues within two years, driven by operational efficiency and sustained innovation across Personal AI and Enterprise AI.
AI-led product innovation, premium mix, print diversification, cost actions and cash returns support HP’s long-term earnings and competitive positioning.
HPQ carries a Zacks Rank #2 (Buy), while LNVGY carries a Zacks Rank #3 (Hold). Price appreciation, prioritization of capital returns and cash flow stability give HP an edge over Lenovo. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
7 Best Stocks for the Next 30 Days
Just released: Experts distill 7 elite stocks from the current list of 220 Zacks Rank #1 Strong Buys. They deem these tickers "Most Likely for Early Price Pops."
Since 1988, the full list has beaten the market more than 2X over with an average gain of +23.9% per year. So be sure to give these hand picked 7 your immediate attention.
See them now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
HP Inc. (HPQ): Free Stock Analysis Report
Lenovo Group Ltd. (LNVGY): Free Stock Analysis ReportThis article originally published on Zacks Investment Research (zacks.com).
Zacks Investment Research